
Car finance scheme challenge to be heard in February 2027 — what it means for your claim
The hearing date is now fixed
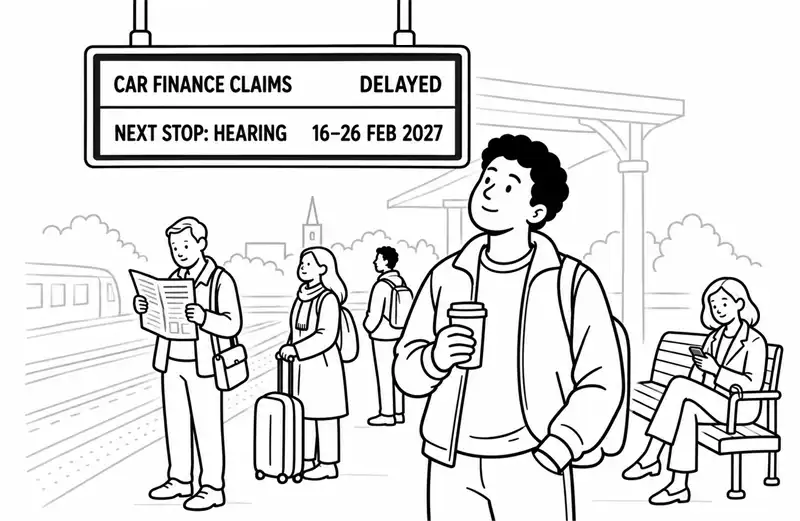
The Financial Conduct Authority (FCA) has confirmed that the Upper Tribunal will hear the legal challenges to its motor finance redress scheme from 16 to 26 February 2027, with a judgment expected in the months that follow.
The date was set at a case management hearing on 5 and 6 October 2026. Back in July, the Tribunal had offered two possible windows — 14 to 18 December 2026 or 16 to 26 February 2027 — depending on whether the parties needed extra time for evidence. At the October hearing, the Tribunal allowed the parties to rely on expert evidence and ordered the FCA to disclose more of the data behind the scheme, so the later February window is the one that has been fixed.
The scheme is being challenged by three lenders — Volkswagen Financial Services, Mercedes-Benz Financial Services and Crédit Agricole Auto Finance — and by the group Consumer Voice. The FCA says the scheme is the quickest, fairest and most efficient way to compensate consumers and that it will defend it robustly.
Compensation payments are still paused
The scheme remains partially suspended. Until the legal process concludes, lenders do not have to calculate or pay compensation under the scheme, or send letters telling people how much they are owed.
In practice, that means final outcomes — and payments — are on hold until the Tribunal gives its judgment after the February hearing.
Complaints are still being worked on
The pause doesn't mean nothing is happening. The FCA has told lenders to keep preparing for the scheme and progress complaints as far as possible. While they can't settle claims yet, lenders must continue to:
- Log and review newly submitted complaints
- Gather the data on commission arrangements and keep finance agreement records
- Investigate whether each agreement falls within the scheme
This groundwork means that, if the scheme goes ahead, lenders should be in a position to move more quickly once the suspension is lifted.
"Not owed compensation" letters still go out
The pause only covers paying out compensation. If a lender investigates a complaint and decides the customer is not owed anything under the scheme, it must still tell them, within the scheme deadlines.
The FCA has said lenders should tell people who are not owed compensation:
- By 18 November 2026 — if you complained by 30 June 2026 about an agreement that started on or after 1 April 2014
- By 18 January 2027 — if you complained by 31 August 2026 about an agreement that started before 1 April 2014
- Within 5 months — for complaints made later
Some people may not hear anything until the legal process is over, so not receiving a letter doesn't necessarily mean you are owed compensation. If you think a lender's decision is wrong, you can ask it to review the decision and then refer the complaint to the Financial Ombudsman Service.
If you're a Refund Club client and your lender tells us it doesn't believe you're owed compensation, we'll let you know and explain your options.
Existing Ombudsman cases carry on
If your complaint had already been referred to the Financial Ombudsman Service before the redress scheme rules were introduced, that investigation continues and remains under review — it isn't frozen by the suspension.
When could compensation be paid?
That depends on what the Tribunal decides:
- If the scheme is upheld (and not appealed), the FCA has said it expects payments under the scheme to begin in 2027.
- If the scheme is changed or overturned, compensation could be delayed to 2028 or later while a revised approach is put in place — or lenders could be told to deal with complaints individually under the usual complaint rules.
The FCA has told lenders to plan for every outcome, including the scheme being quashed. Either way, the suspension is about timing, not entitlement: if you had car finance between 6 April 2007 and 1 November 2024, you remain within scope.
Key dates
- 2 July 2026 — Upper Tribunal partially suspends the scheme
- 5–6 October 2026 — case management hearing
- 18 November 2026 — deadline for "not owed" letters (agreements from April 2014, complaints by 30 June 2026)
- 18 January 2027 — deadline for "not owed" letters (agreements before April 2014, complaints by 31 August 2026)
- 16–26 February 2027 — Upper Tribunal hears the legal challenges
- Spring 2027 onwards — judgment expected in the months after the hearing
What should you do now?
- If you're already a client, you don't need to do anything. We'll keep managing your claim and will update you as soon as there are further developments.
- If you haven't claimed yet, check whether you had car finance between April 2007 and November 2024. You can complain directly to your lender for free, or use a firm like us to handle it for you — getting your claim registered now means it's ready to move as soon as the pause lifts.
- Only sign up with one firm. Using more than one claims firm for the same agreement can mean paying more than one fee.